Chapter 2·Part I, Deciding to Raise
How Rounds Happen
Securing money for a startup happens in one of two ways: a founder asks for capital and gets it, or an investor offers capital and the founder takes it. In practice, there are three primary paths to a closed round.
1. Externally obvious hyperbolic growth. When a company grows so fast that the growth is obvious to outsiders, investors will compete to fund it. This is the dynamic that played out for OpenAI and Anthropic in their growth rounds as investors pummeled them with cash at increasingly astronomical valuations. You can tell if you're in this category if multiple investors are chasing you with term sheets without concern for valuation and without being prompted. If that’s not you, don’t worry. Vanishingly few companies are in this category. Anthropic famously was rejected by dozens of top VC firms across multiple early rounds. Even in these happy cases, there are a large number of ways to screw up a good thing. We’ll discuss the right and wrong way to navigate this dynamic later.
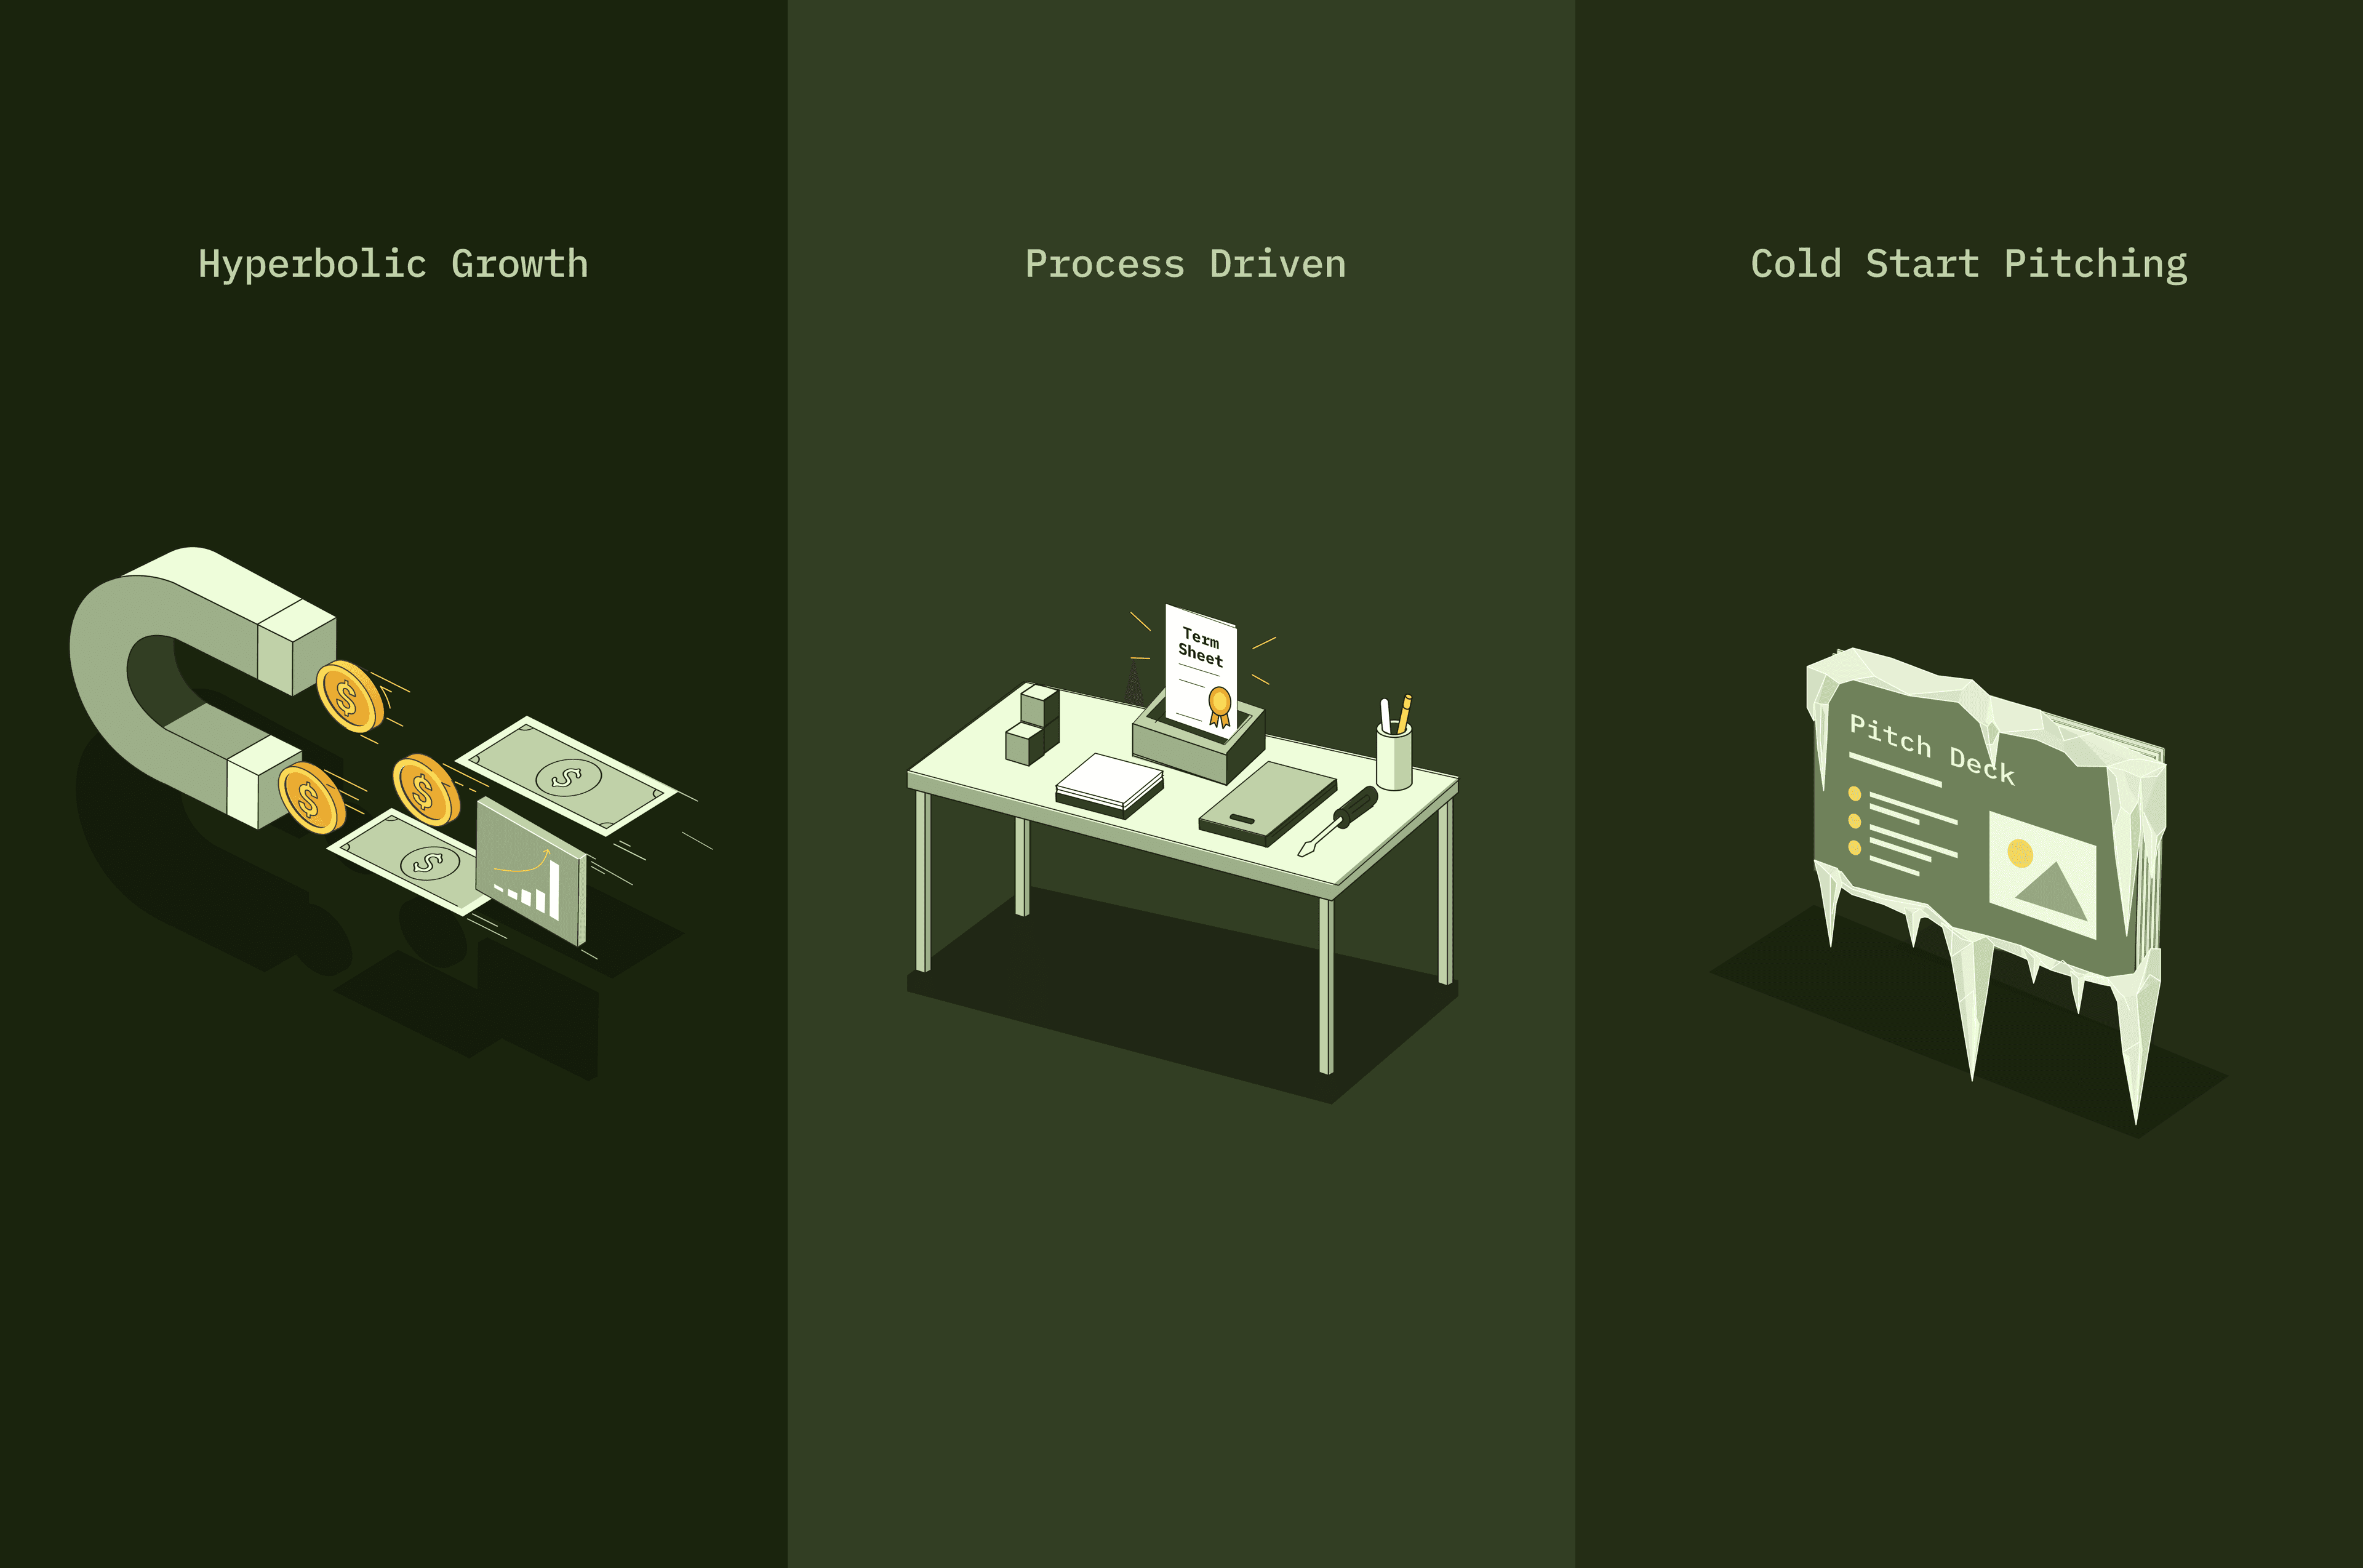
2. Process driven fundraising. This is where we are going to spend most of our time since this is how the overwhelming majority of rounds happen. An ideal outcome of a great process driven fundraise is what funding announcements call a “pre-empt.” This usually means that an investor who already has a relationship with a company offers terms before the founder “starts” a formal process. Investors do this to win deals by being first and usually think it is their idea. But the truth of the best fundraises I’ve seen is that great founders orchestrate these offers.
This investor behavior seemed rare before 2020, but has become increasingly common across a wide range of rounds for attractive AI and deeptech companies. That said, a real pre-emptive offer is a written term sheet. Full stop. Anything less, however enthusiastic, is simply an expression of interest. Investors who give a pre-emptive verbal offer often bedazzle founders, but these non-committal offers are usually attempts to start a one-on-one fundraising process on the investor's timeline rather than yours.
Pre-emptive offers can often seem magical to outsiders but they are almost always the result of strong groundwork. That work requires a founder to cultivate investor relationships and strategically manage information well before fundraising becomes required. For all intents and purposes, most pre-emption is the result of a process, but it’s a warm process vs. a cold one. This is perhaps the most critical lesson: founders who trigger an offer before they pitch broadly create both optionality for themselves, and useful momentum throughout the rest of the fundraise.
Once you have a pre-emptive term sheet, we have an entire chapter dedicated to the framework for taking one versus using it to run an accelerated process. Nearly everything else you’re going to read is meant to help you get to that point.
3. Cold start pitching. Starting a pitch process without first laying the groundwork and relationship building is the hardest, and honestly worst, way to fundraise. You might have to do it if you’re suddenly running out of money or facing a different existential thread. But especially in the AI era it often leads to poor terms, or no terms at all.
This guide is meant to avoid going into fundraising cold turkey. Building the foundation of strong investor relationships, data-driven pitches, and parallel fundraising are critical to ensuring a successful outcome.