Introduction
Preamble
Once upon a time, not so long ago, fundraising worked like a ladder. Companies started with very little progress and raised a small amount of money to hit some arbitrary proof point. They'd hit that target, get bigger in the process, and raise a larger amount of money against the next proof point. Repeat all the way up to the IPO. At each rung, investors evaluated companies against somewhat objective measures of progress: metrics. Metrics never told the whole story, and what actually mattered was always the distant future. But they were useful. They gave founders and investors alike a shared language for what a seed was, what an A was, what a B was.
The first time I set out to write a guide for fundraising, that ladder was a mostly reliable framework. I was building Y Combinator's Series A program, and the guide I wrote with my colleague Janelle Tam was built around a clean model: seed rounds were raised on promise, Series Bs were raised on metrics, and the Series A was the awkward, fascinating bridge between the two. That model was right at the time, and it helped hundreds of companies raise billions of dollars.
It's not right anymore.
In the last few years, metrics lost most of their value as an objective standard. Numbers started getting ludicrously big, unimaginably fast. First companies went from zero to $10 million in 18 months, then zero to $100 million, then zero to a billion in revenue in under two years. When one company grows that way, you can explain it away. When it becomes the baseline, everyone loses the ability to judge what's normal and what's exceptional. Technology stopped working as a differentiator around the same time; nearly every revolutionary piece of software shipped in the past year was replicated by competitors within months, and that's as true for the most advanced AI models as it is for SaaS. Markets and ideas are just as copyable.
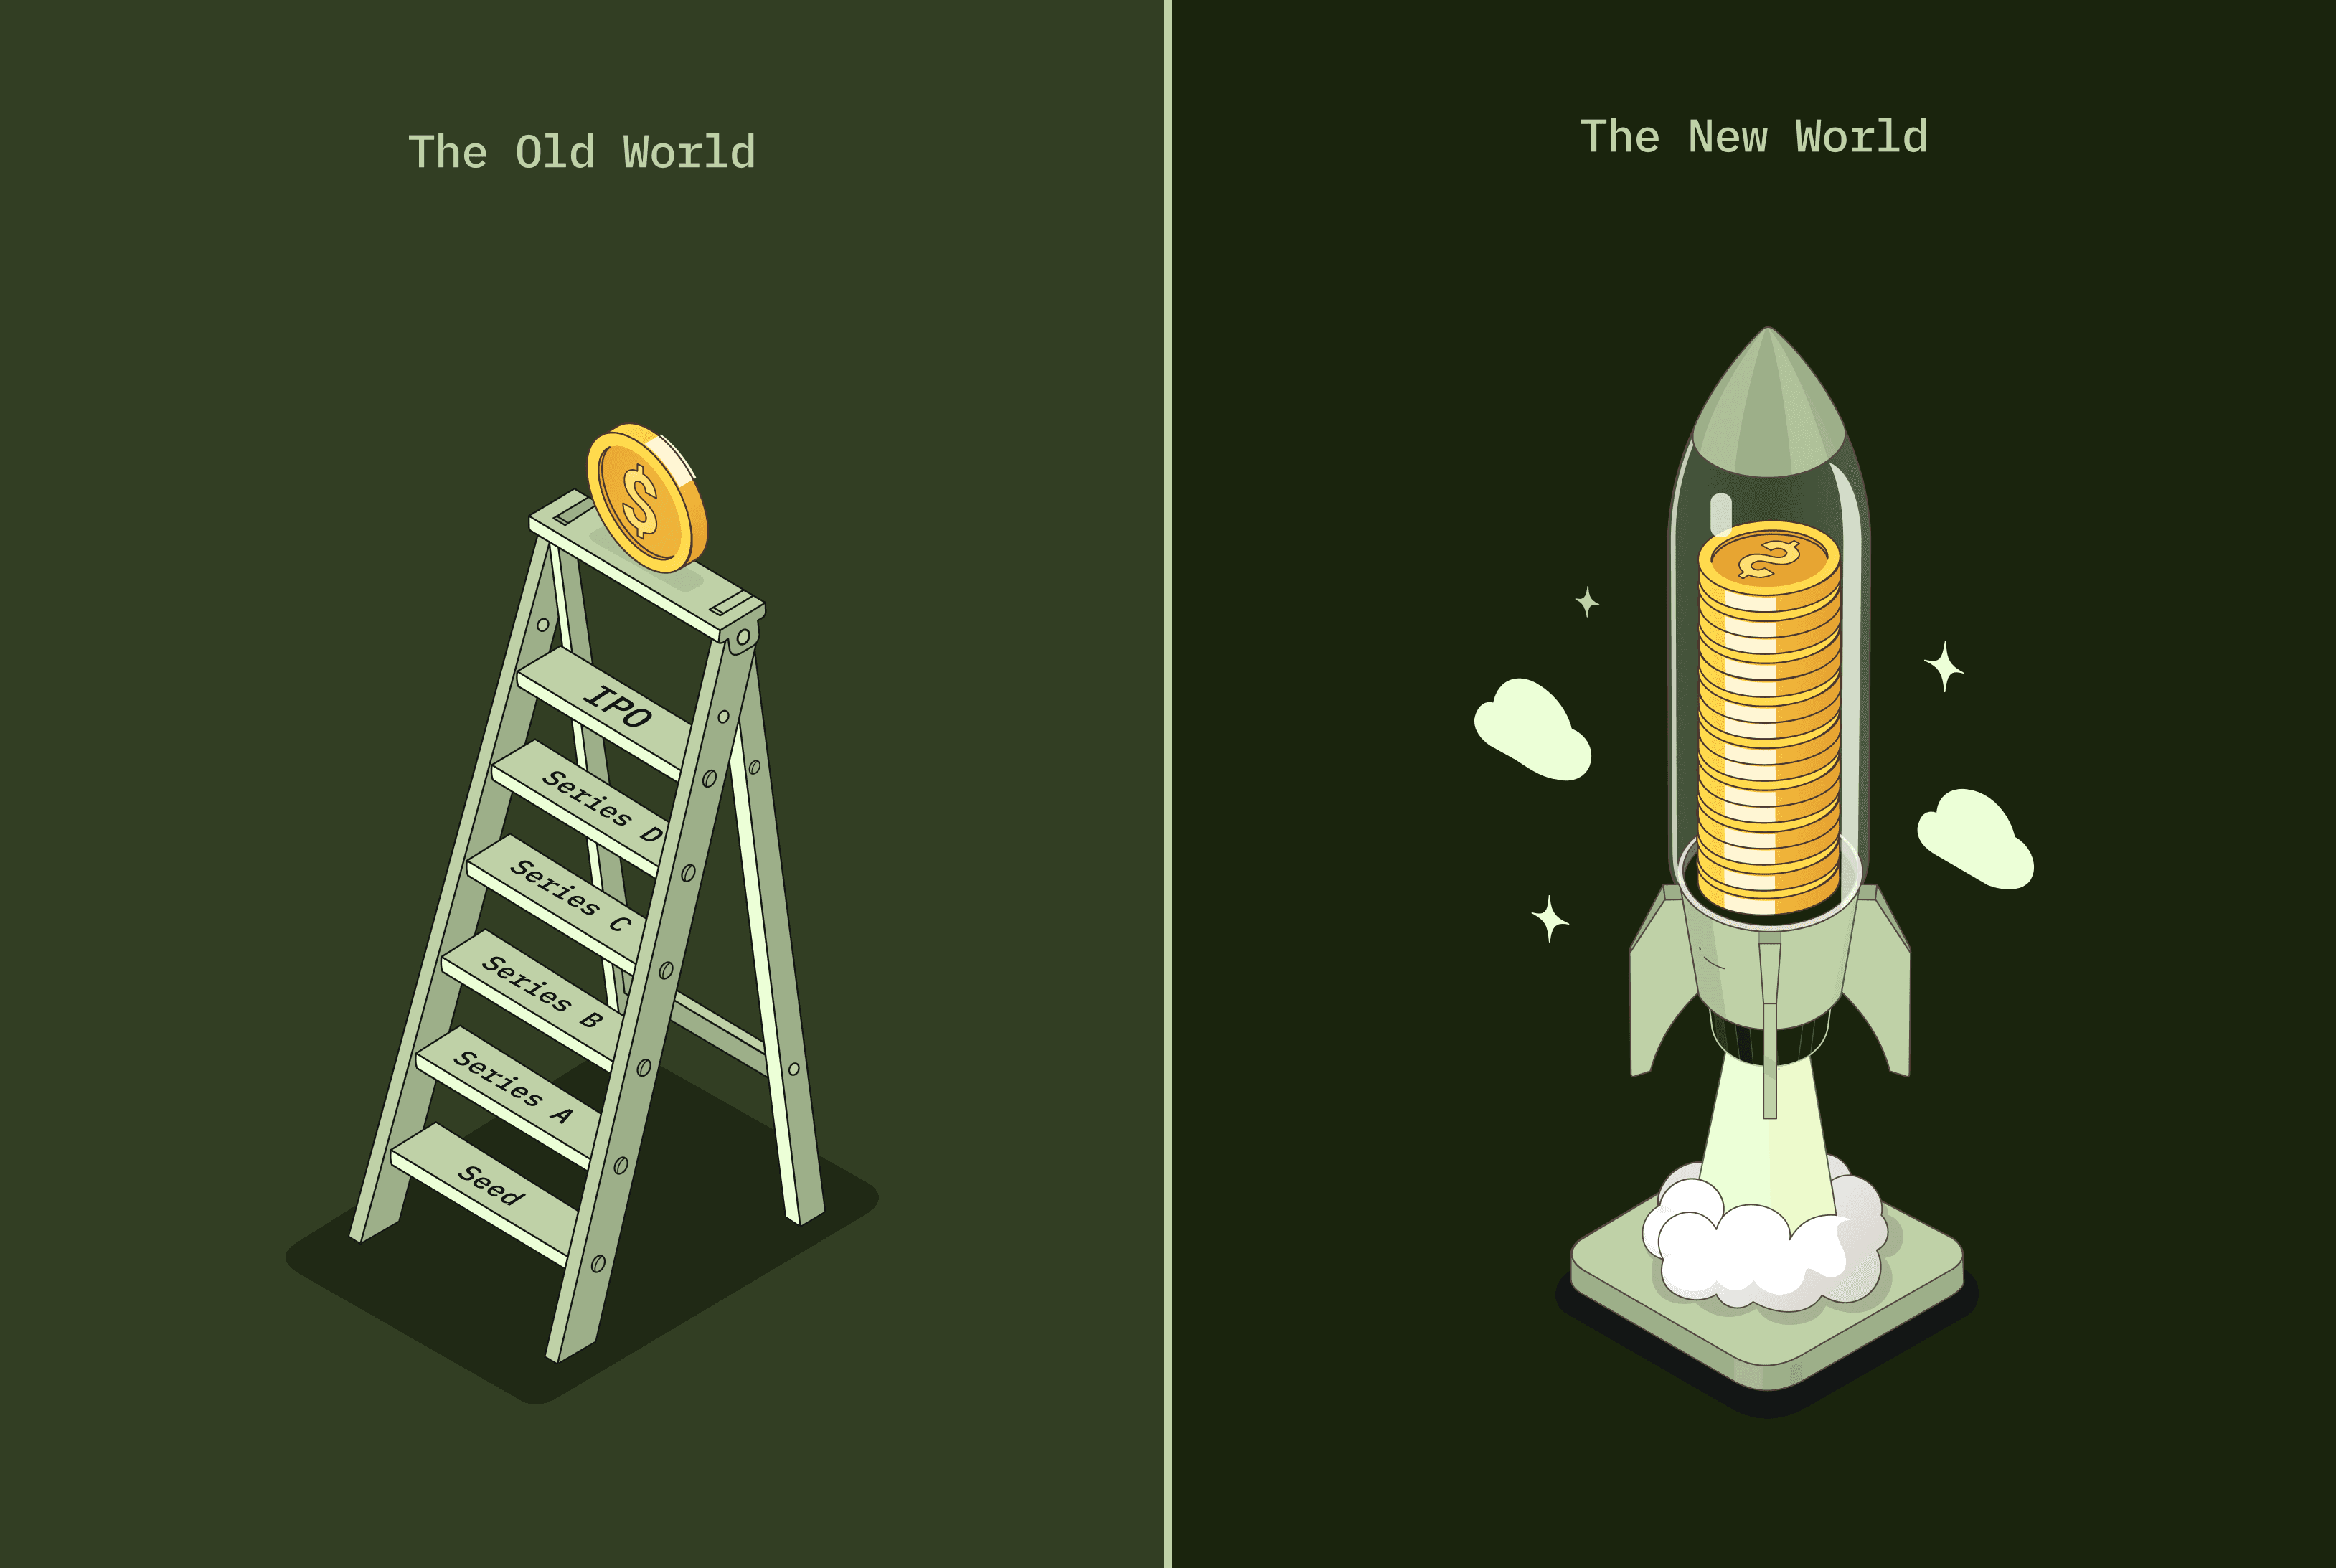
Strip all of that away and one fixed point remains: the founder. Backing exceptional founders was always the primary driver of a seed round. Now it's the primary driver of nearly every round, sometimes all the way through the Series C and D. Metrics still matter, but as a signal of interestingness, evidence that the founder is who investors hope they are, rather than a gate you clear to earn the next letter. In a real sense, every round is basically seed now.
Yet while the evaluation of companies got fuzzier, the process of raising money didn't. A raise still has mechanics. There is still a right way to prepare, a right way to build materials, a right way to schedule meetings so that investors compete instead of collude, a right way to read a term sheet, and a right way to close. Those mechanics are learnable. They are largely the same whether you're raising a $15 million SAFE or a $500 million round. Getting them wrong still kills fundraises for good companies every single week. That collision between fuzzy evaluation and unforgiving process is what this guide is about. The two questions every founder has to answer are when do I raise? and how do I actually do it? I'm going to answer both.
This guide is based on my experience working with thousands of founders on their raises. Through YC and Magid, I've worked directly with founders raising over $6 billion of capital at these stages, and what you'll read here are the lessons learned, adapted, and improved over those rounds, including plenty learned from watching raises fail. In my head I call the method Process Driven Fundraising, but that abbreviates to "PDF," which I obviously can't use.
A word on scope. I won't spend time on the mechanics of first-money-in SAFEs from angels or accelerators. Enough has been written about those, and frankly, they're the easy part. And at the top end, this guide runs out at true growth rounds. The moment an investor starts asking what multiple of revenue they're paying, you've crossed into a different sport with different rules
Here's the cleanest way I know to name that line. Forget the letters: there are venture rounds and there are growth rounds. A venture round prices an unknown future off data that is scant relative to the size of the outcome being claimed. A growth round feeds a known machine that produces relatively known outputs. This guide is about venture rounds, and its core claim is that within venture, every bet is functionally a seed bet: the question is always whether the founder in front of you can achieve something massive. Everything in between, the priced rounds, the process rounds, the rounds where a single lead sets terms and takes a board seat, is the territory of this guide.
Here's how the guide is organized:
The Speed Run. A tactical pass through an entire raise, start to finish, with minimal theory. Think of it as an executable table of contents; use it to find the part of the guide you need right now.
Preparing to Raise. Everything that (should) happen before you pitch a single investor: deciding when to raise, crafting your story, cultivating relationships, and sizing the round.
Deliverables. The materials (deck, memo, and pitch) and how to make each one do its actual job, which is to make investors afraid to pass on you.
Process. The raise itself: how to create leverage by running an auction, how to schedule, what information to share and when, and how to avoid optimizing yourself out of a good outcome.
Closing. Term sheets, negotiation, choosing the investor who'll sit on your board for the next decade, and actually getting the money in the bank.
Special Rounds. The situations that don't follow the standard playbook: pre-emptive offers, bridge rounds, and an insiders playbook of how today's very largest rounds actually come together.
Throughout the guide you'll find commentary from founders about the specifics of their own rounds, kept anonymous because that's the only way anyone tells the truth about fundraising. And each section includes practical exercises designed to be used while you prepare and execute your raise.
Two warnings before we start. First, following this guide is not a guarantee of a successful raise. There's no such thing. Second, there is no rule that says a successful company needs to raise venture capital at all. Money is a means to an end, and the end is the company. This guide exists for founders who've decided that raising is the right move and want to do it well.
So let's do it well. And then get back to work.